
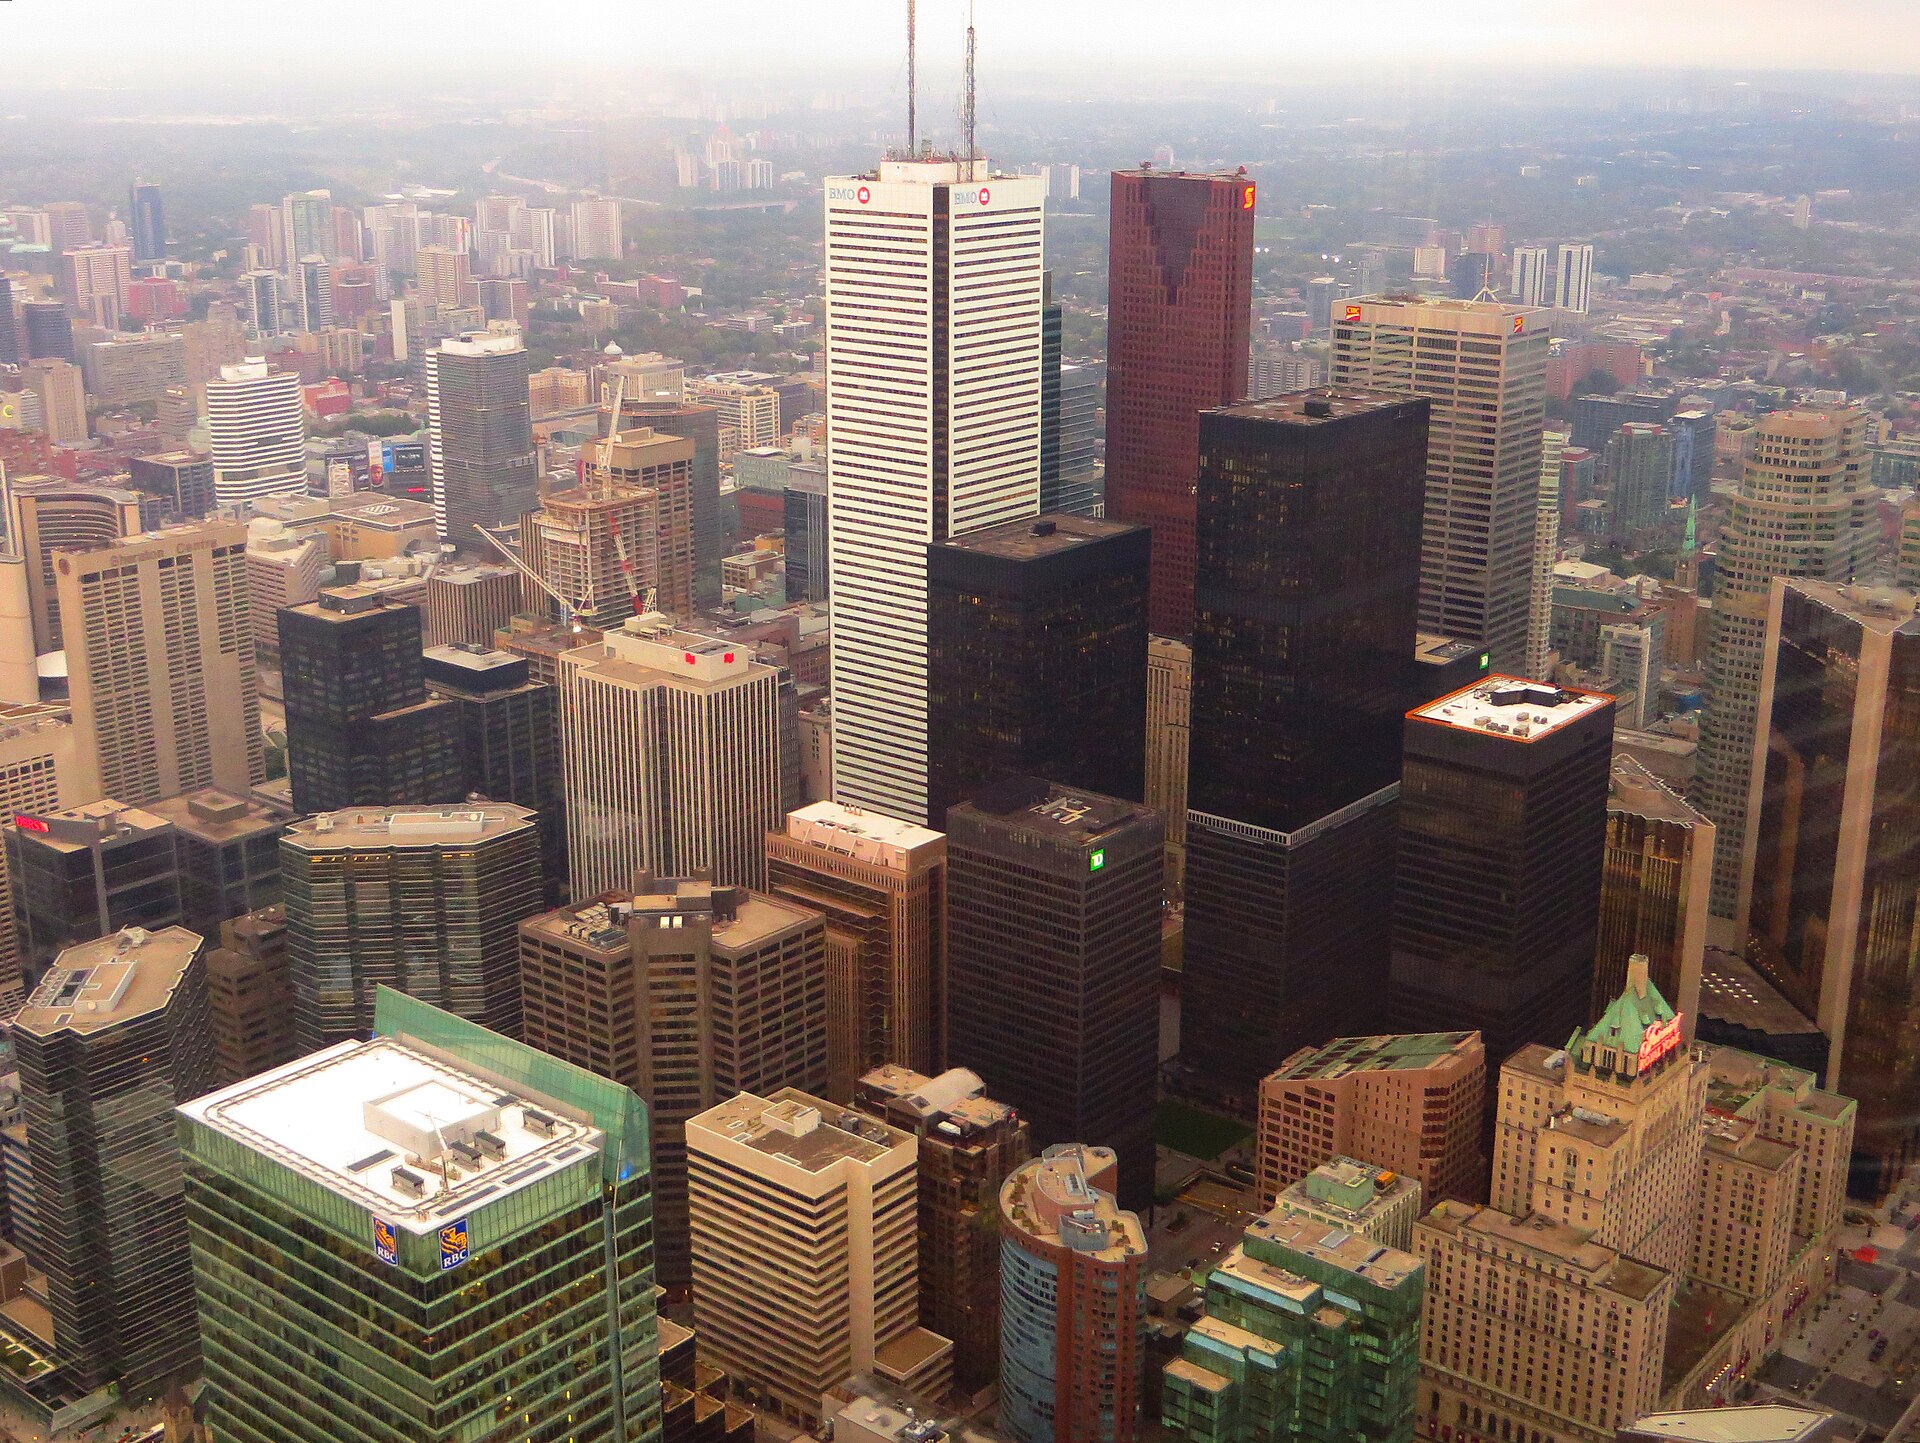
Canada’s six largest banks held 95 per cent of all assets on the books of banks that report to the federal banking regulator at the end of August 2026, up from 93.2 per cent three years earlier, according to a Canada News Media analysis of regulatory filings published by the Office of the Superintendent of Financial Institutions.
The rise followed two takeovers that Ottawa approved: Royal Bank of Canada’s purchase of HSBC Bank Canada and National Bank of Canada’s purchase of Canadian Western Bank. In each case the jump shows up in a single month of OSFI’s data.
OSFI’s monthly consolidated balance sheets, which every bank files with the regulator and which OSFI publishes on the federal open data portal, list total assets of $10.21 trillion for all banks at Aug. 31, 2026. Royal Bank, Toronto-Dominion Bank, Bank of Nova Scotia, Bank of Montreal, Canadian Imperial Bank of Commerce and National Bank together reported $9.70 trillion of that. The share was 93.2 per cent in August 2023, 92.8 per cent in August 2016, 90.7 per cent in August 2006 and 90.8 per cent in August 1996, the first year in the dataset.
The same six banks reported 93 per cent of the $1.97 trillion in insured and uninsured residential mortgages on bank balance sheets, and 93 per cent of the $2.23 trillion in personal deposits we tallied from the filings, which combines individuals’ demand and notice deposits with their fixed-term deposits, including those held in tax-sheltered accounts.
Royal Bank alone held 26.2 per cent of all bank assets in August 2026, or $2.68 trillion, up from 23.2 per cent in August 2021. TD was second at 20.6 per cent, followed by Scotiabank at 15.2 per cent, BMO at 15.1 per cent, CIBC at 11.6 per cent and National Bank at 6.3 per cent.
The month-by-month figures show where the change came from. The Big Six share was 93.45 per cent at the end of March 2024, the last month HSBC Bank Canada filed its own balance sheet with OSFI, and 94.55 per cent at the end of April 2024. The federal government had approved the HSBC sale with conditions in December 2023. The share rose again from 94.59 per cent at the end of January 2025 to 95.23 per cent at the end of February 2025, the month National Bank’s reported assets went from $483.8 billion to $555.3 billion. National Bank said in December 2024 that the federal finance minister had given final approval to its Canadian Western Bank deal and that it expected to close it on Feb. 3, 2025. The Department of Finance had run a public consultation on that deal.
One measure of the change: the combined assets of foreign-owned bank subsidiaries in Canada fell from $147.5 billion in August 2021 to $32.7 billion in August 2026, because HSBC Bank Canada, the largest of them, is now part of Royal Bank.
The banking figures have limits. The balance sheets are consolidated, so the big banks’ totals include their operations in the United States and elsewhere, and the share is a share of bank assets, not of the Canadian lending market. The data cover only institutions regulated by OSFI. They leave out provincially regulated credit unions and caisses populaires, including Desjardins, which compete with the banks for mortgages and deposits in many provinces. In approving the HSBC deal, the federal government said the Competition Bureau had concluded the transaction would not substantially lessen competition.
Wireless service shows a similar pattern. The Canadian Radio-television and Telecommunications Commission’s latest retail mobile data, which cover 2024, show that Rogers, Bell and Telus, counted with their discount “flanker” brands, took 89.4 per cent of retail mobile revenue and served 85.9 per cent of mobile subscribers. Every other provider combined, a group that includes Quebecor’s Vidéotron and Freedom Mobile, SaskTel and regional carriers, earned 10.6 per cent of revenue.
That smaller group’s share rose from 7.6 per cent in 2013 to a high of 11.7 per cent in 2021, then slipped to 10.6 per cent by 2024. Rogers’ own revenue share went from 30.8 per cent in 2022 to 31.9 per cent in 2023, the year it completed its takeover of Shaw Communications, and 32 per cent in 2024. Bell had 30 per cent and Telus 27.4 per cent.
The CRTC data also show the industry’s mobile profit margin before interest, taxes, depreciation and amortization was 48.2 per cent in 2024, compared with 43.3 per cent in 2013. Average monthly revenue per mobile subscriber was $69.16 in 2024, down 1.5 per cent from $70.23 in 2023.
The figures come as Quebecor, the owner of Freedom Mobile, has proposed to buy Telus. Any such deal would need reviews by the Competition Bureau and other federal bodies. Nothing in the regulators’ data says any bank or carrier has misused its position, and high market shares are not illegal under the Competition Act. The numbers show how few firms Canadians now deal with for their mortgages, savings and phone plans, a question at the centre of the federal competition debate.
Several things help explain the concentration. A few national banks have dominated Canadian banking for decades, and in 1998 the federal finance minister rejected proposed mergers among four of them, so recent growth at the top has come from buying smaller and foreign-owned banks rather than from mergers among the largest. Wireless networks are expensive to build across a large country with a small population, and federal spectrum auctions and wholesale access rules have been the main tools for adding competitors. Earlier parts of this series found that more Canadian businesses closed for good than opened in 2025 and that the Competition Bureau opened fewer abuse-of-dominance investigations as complaints rose. We have also reported that Rogers brands doubled their telecom complaints in a year.
This story is part of Canada News Media’s series on competition and small business in Canada. Also in the series: Tribunal has yet to let a private competition case proceed.
If you find reporting like this useful, consider supporting Canada News Media, an independently owned Canadian newsroom.
How we checked: We downloaded OSFI’s M4 consolidated balance sheet data for banks on Nov. 18, 2026, through the open data portal’s datastore, which holds each bank’s filings, and pulled total assets (data point 1045), insured and uninsured residential mortgages (0540 and 0542) and individuals’ deposits (0877, 0616 and 0618) for August of 1996, 2001, 2006, 2011, 2016, 2021 and 2026, plus monthly total assets around each takeover. We divided the six banks’ consolidated figures by OSFI’s “Total All Banks” line, which includes domestic banks, foreign bank subsidiaries and foreign bank branches and does not double count subsidiaries of other banks. August 2026 is the latest month for which all six banks have reported. Wireless figures are taken directly from the CRTC’s Communications Market Report open data for the retail mobile sector (supplementary table 1, figures 2, 9, 12 and 13), where “Top 3” includes Bell, Rogers, Telus and their flanker brands. Shares are as the regulators report them, rounded. No finding of wrongdoing by any bank, carrier or regulator is made in this analysis. Our calculations are available on request.
Follow Canada News Media
Get the day's top Canadian stories and our two daily 60-second news videos wherever you scroll.
X Threads Facebook Instagram LinkedIn TikTok YouTube Pinterest Reddit Substack Flipboard Newsletter RSS