
Advantage Energy Ltd. cut its net debt to $233.0 million at the end of the third quarter, down 59 per cent from a year earlier, after closing the $325.4 million sale of its Wembley-area assets, the Calgary-based Montney producer said in results released Oct. 29.
The TSX-listed company (TSX: AAV) reported net income of $56.4 million, or 34 cents a share, for the three months ended Sept. 30. That compares with a loss of $43,000 in the same quarter of 2025. Included in the quarter was a $90.1 million gain on the Wembley sale, so the profit is not a measure of day-to-day operations.
The operating numbers are steadier. Adjusted funds flow was $96.8 million, or 58 cents a share, up about 34 per cent from $72.4 million a year earlier. Natural gas and liquids sales rose 45 per cent to $190.2 million from $130.8 million, according to Advantage’s third-quarter release on Newswire.
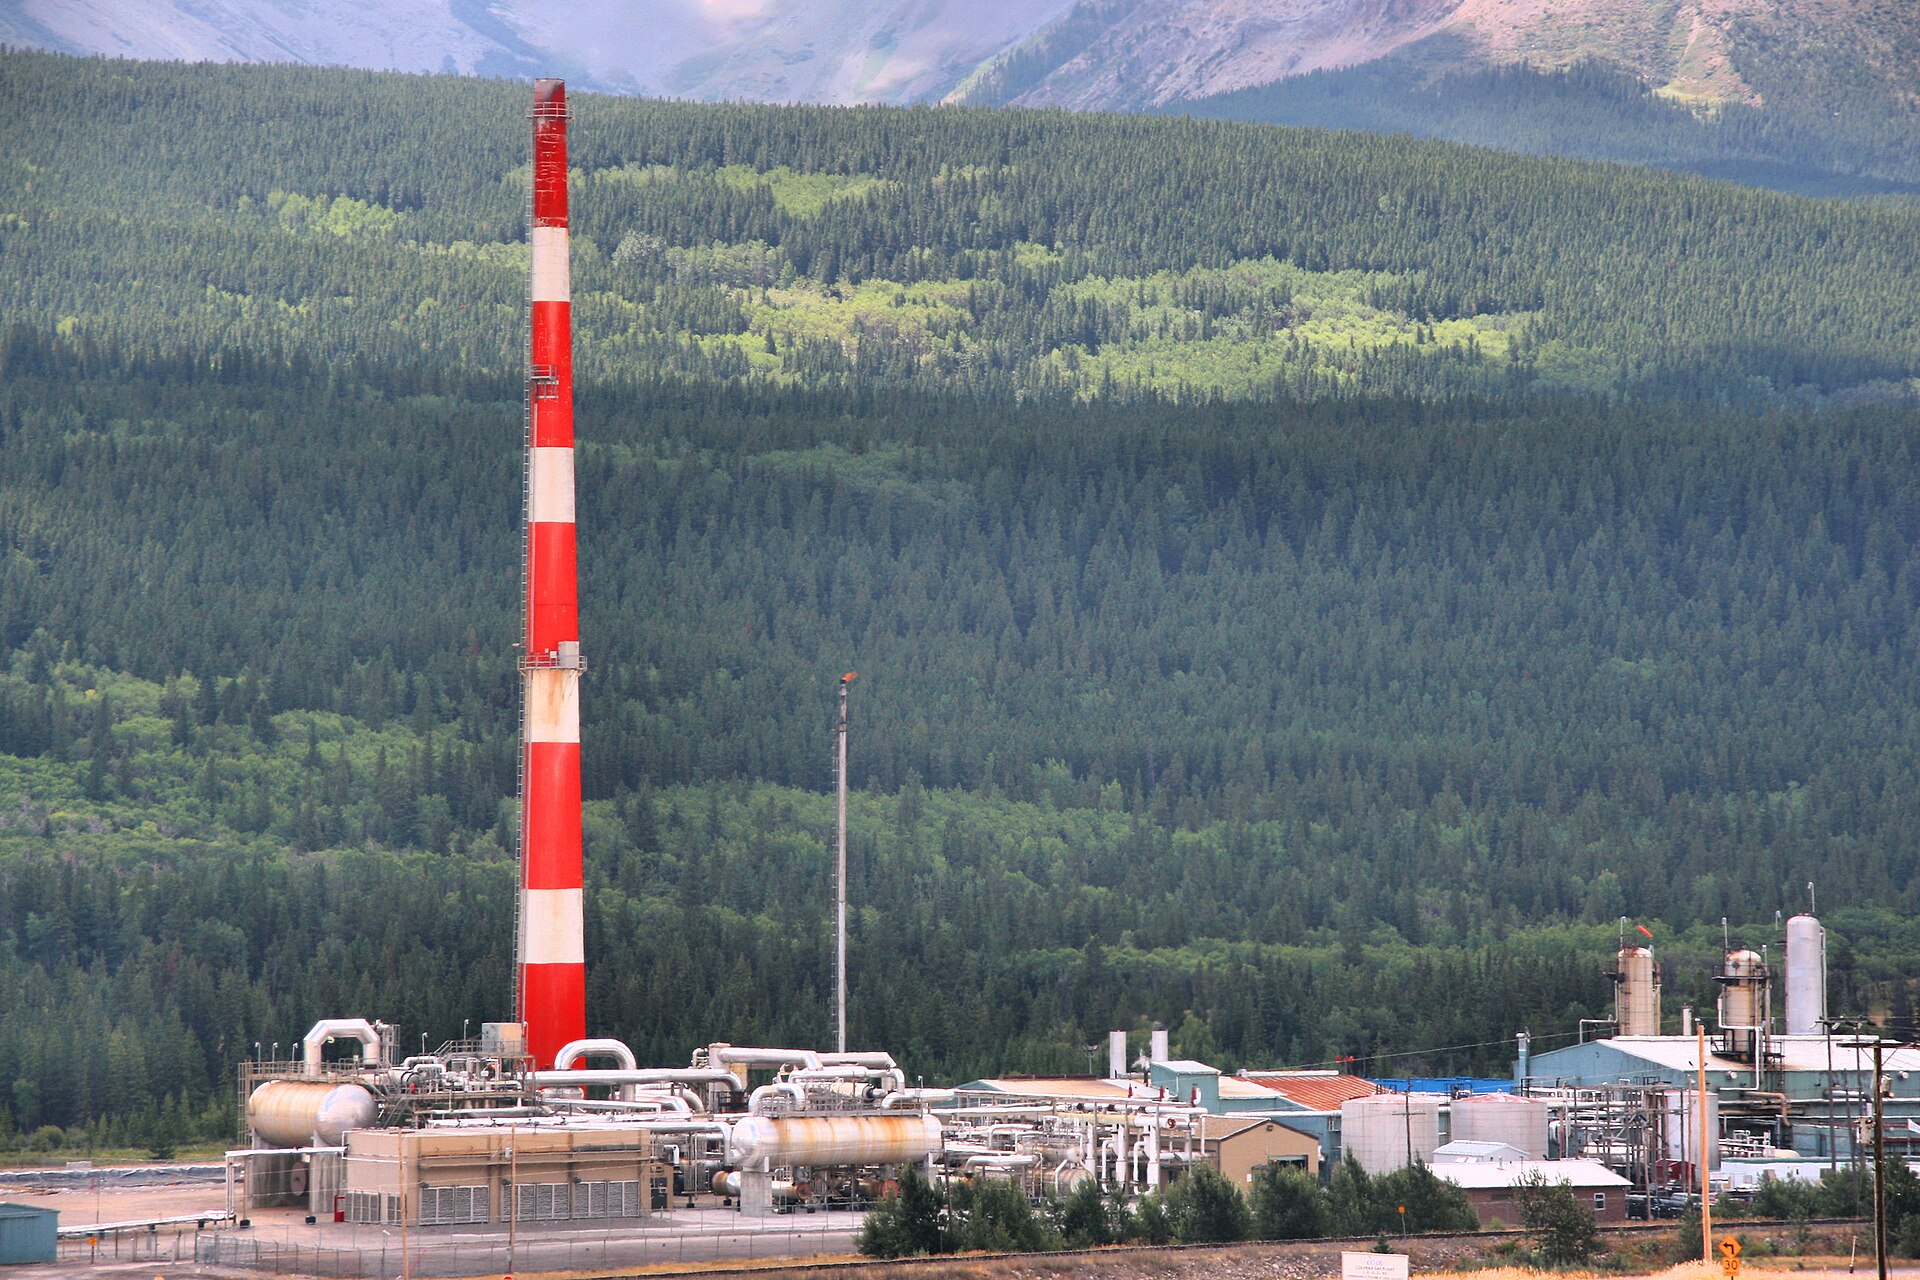
Production averaged 86,964 barrels of oil equivalent a day, about 22 per cent higher than the 71,482 boe/d recorded in the third quarter of 2025 and 23 per cent above the second quarter of this year. The company credited the commissioning of its Progress Gas Plant and the completion of a planned 21-day turnaround at the Glacier Gas Plant earlier in the year. Natural gas made up 452.0 million cubic feet a day of that total.
Prices helped. Advantage’s realized natural gas price, including hedging gains, was $2.69 per thousand cubic feet, up from $2.37 a year earlier, while liquids fetched $86.29 a barrel, up from $78.13. Royalties took a bigger bite, rising to $2.98 per boe from $1.87. The operating netback, what the company keeps per barrel after royalties and operating and transportation costs, edged up to $13.92 from $13.58. Those comparisons are Canada News Media’s calculations from the figures in the release.
Costs fell against the second quarter. Operating expense dropped 16 per cent to $4.86 per boe, transportation expense fell 10 per cent to $3.71, and general and administrative plus interest expense fell 41 per cent to $1.73. Advantage said the improvement reflects a more focused asset base, greater use of infrastructure it owns, and lower debt.
For Alberta, the quarter shows what the gas price slump looks like from inside a producer. Advantage said direct exposure to the weak AECO benchmark price has fallen to about 12 per cent of production in the fourth quarter, and it has hedged about 46 per cent of forecast fourth-quarter gas output, 37 per cent in 2027 and 35 per cent in 2028. Shifting sales away from AECO is one way Montney companies are trying to shield themselves from low Alberta hub prices.
Free cash flow was $35.9 million, which the company said all went to share buybacks. Advantage has repurchased about six million shares so far this year, or 3.6 per cent of the shares outstanding at the end of 2025. It plans to buy back up to five per cent of its shares in the second half of 2026 and up to a further 10 per cent in 2027.
Federal tax policy is also in the picture. Advantage said Ottawa’s proposed Productivity Mega Deduction, announced by the Department of Finance on Sept. 15, would let it immediately deduct most new capital spending. The company expects that to push the date it becomes cash taxable to 2031 from 2028. The deduction is a proposal, not law. Our earlier look at the measure described it as a timing shift, not a cut.
On the drilling side, two new wells at the Progress Montney pad were brought on production Oct. 27 after what the company called encouraging 48-hour and 62-hour test rates. Advantage said it expects 30-day initial production results in early December, when it will also release its 2027 budget. It plans two more Progress wells in the first quarter of 2027 and its first open-hole multi-lateral well in the Charlie Lake formation in the fourth quarter.
The results come as Montney consolidation continues. Ovintiv recently agreed to buy Logan Energy in a $1.26-billion Montney deal, and crude has stayed elevated amid Middle East supply fears, with Brent near US$116 earlier this week.
Advantage’s management is scheduled to discuss the results on a conference call at 8 a.m. MT on Oct. 30. The figures exclude Entropy Inc., its carbon-capture subsidiary, which reported net debt of $394.7 million.
If you find reporting like this useful, consider supporting Canada News Media, an independent Canadian newsroom with no corporate parent.
Follow Canada News Media
Get the day's top Canadian stories and our two daily 60-second news videos wherever you scroll.
X Threads Facebook Instagram LinkedIn TikTok YouTube Pinterest Reddit Substack Flipboard Newsletter RSS